On 8 October 2026, Singapore's stock market delivered a sharp reminder that markets do not always move in the direction investors expect.
The Straits Times Index (STI) fell 3.5% in a single trading session, closing at 5,412.96 points. Singapore's three major banks were among the hardest hit, with UOB falling 5.2%, DBS declining 4.7% and OCBC dropping 4.3%. Rising global bond yields, concerns about bank earnings and profit-taking contributed to the sell-off.
For investors watching their portfolios, it was an uncomfortable day.
Perhaps you checked your investment account and saw your portfolio value fall. Perhaps you wondered whether it was time to sell before things got worse. Or perhaps you started questioning whether investing in the stock market was the right decision in the first place.
These reactions are understandable.
Our investments often represent years of hard work, savings and sacrifices. For those approaching retirement, the money in their portfolios may be even more meaningful because it represents the lifestyle they hope to enjoy in the years ahead.
But before reacting to the headlines, there is a more important question to ask:
Does one bad day in the stock market change the reasons you invested in the first place?
Nobody can predict exactly when markets will rise or fall. What we can do, however, is understand the fundamentals of investing and build a financial plan that accounts for uncertainty.
Here are five investment fundamentals worth remembering when markets fall.
1. Know Your Investment Time Horizon
One of the first questions every investor should ask is simple: When will I need this money?
The answer matters because money intended for different purposes should not necessarily be invested in the same way.
Consider someone who is 35 years old and investing for retirement at 65. They have approximately 30 years before they expect to need their retirement savings. A market decline today may be unsettling, but they may have considerable time to navigate short-term volatility.
Now consider someone who is 62 and plans to retire next year.
If a substantial portion of their retirement savings is invested in the stock market, a sharp decline could have a more immediate impact on their plans. They may have less time to wait for a recovery, particularly if they need to withdraw money to cover their living expenses.
The two investors may own similar investments, but their financial needs are very different.
This is why an investment strategy should begin with your goals and time horizon, rather than simply chasing the highest possible return.
Money required for near-term expenses generally needs greater accessibility and stability. Money allocated to longer-term goals may have more room to take investment risk, depending on the investor's circumstances and ability to withstand losses.
A longer time horizon can provide greater flexibility, but it does not guarantee that an investment will recover or that losses will eventually be reversed.
The key is to understand what each portion of your money is meant to achieve.
Before making a decision during a market downturn, ask yourself:
- What is this money intended for?
- When am I likely to need it?
- Can I afford to leave it invested if markets remain weak for an extended period?
The more clearly you understand your investment time horizon, the easier it becomes to distinguish between short-term market noise and changes that genuinely affect your financial goals.
2. Diversification Matters More Than You Think
The STI's decline also highlights the importance of diversification.
On 8 October, all three major Singapore banks fell sharply. Given their significant influence on the local market, their declines placed considerable pressure on the STI.
For investors whose portfolios are heavily concentrated in Singapore bank shares, the impact may have been even more pronounced.
Owning several different stocks does not automatically mean your portfolio is well diversified.
Imagine an investor who owns DBS, OCBC, UOB and several other financial-sector companies. Although the portfolio contains multiple investments, many of them may be exposed to similar economic conditions, interest-rate changes and sector-specific risks.
When those conditions turn unfavourable, several holdings may decline together.
Diversification seeks to reduce this dependence on any single investment or source of return.
Depending on an investor's objectives and circumstances, this may involve spreading investments across different companies, industries, geographical markets and asset classes.
For example, a portfolio combining equities, suitable high-quality bonds and cash reserves may behave differently from one invested entirely in equities. Each asset class has its own risks, and diversification cannot prevent all investments from falling together during periods of market stress.
Nevertheless, a well-considered allocation can help reduce concentration risk and make a portfolio less dependent on the performance of one particular market.
This is especially relevant for Singapore investors who may already have significant financial exposure to Singapore through their employment, property and retirement savings.
Your home, job, CPF savings and investment portfolio may each serve different purposes, but it is worth understanding how your overall financial position is exposed to similar economic risks.
The objective is not to diversify for the sake of owning more investments.
It is to build a portfolio that is appropriate for your goals and does not rely excessively on one company, sector or market performing well.
Diversification cannot eliminate investment risk, but it can help prevent one area of weakness from determining your entire financial outcome.
3. Understand What You Own
When markets are rising, it is easy to become comfortable with an investment simply because its price keeps increasing.
When markets fall, that confidence can disappear just as quickly.
Both reactions can be problematic if they replace proper analysis.
A falling share price does not automatically make an investment attractive. Equally, a declining portfolio value does not automatically mean every investment within it is fundamentally unsound.
The important question is whether the underlying reasons for investing remain valid.
For individual shares, this means understanding the business, its earnings, balance sheet, competitive position, valuation and ability to manage changing economic conditions.
For investment funds, it means knowing what the fund holds, how it invests, what fees it charges, what risks it takes and whether its objectives remain aligned with yours.
The same principle applies to investments marketed for income.
A high dividend yield may look attractive, especially to someone preparing for retirement. However, a high yield alone does not establish that an investment is safe or that its distributions will be sustainable.
Dividends can be reduced, asset values can decline, and some investments may expose investors to risks they do not fully appreciate.
Investors should therefore look beyond headline returns and ask how those returns are generated.
Consider these questions:
- Do I understand the underlying investments?
- What could cause them to lose value?
- Are the expected returns reasonable in relation to the risks?
- Are the costs and conditions clear?
- Does this investment still serve the purpose for which I selected it?
These questions become particularly important when markets are volatile, because uncertainty can reveal weaknesses that were less obvious during a period of rising prices.
Do not buy an investment simply because its price has fallen. Do not sell an investment solely because it has fallen either.
Understand what has changed before deciding what to do.
The aim is not to find investments that never fall. It is to understand the risks you are taking and why those investments belong in your portfolio.
4. Match Investment Risk to Your Financial Needs
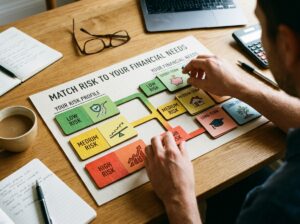
There is no single investment strategy that is suitable for everyone.
A younger investor with stable income, adequate emergency savings and decades before retirement may be able to tolerate more short-term volatility than someone who relies on their investments to fund monthly living expenses.
Even among people of the same age, circumstances can differ considerably.
One person may have a fully paid-up home, substantial savings and other dependable sources of income. Another may still have a housing loan, dependants and limited financial flexibility.
Their ability to absorb investment losses will not be the same.
This is why investment planning should consider more than the returns you hope to achieve.
It should also consider the losses you can withstand, your income needs, your financial commitments and how you might respond when markets become difficult.
A portfolio that looks acceptable when markets are rising may feel very different during a sharp decline.
If a 20% fall in your portfolio would cause you to panic, disrupt your retirement plans or force you to sell investments to cover essential expenses, it is worth examining whether your current allocation is appropriate.
This does not mean everyone should avoid risk. Taking too little investment risk can also create challenges, particularly when retirement may last several decades and inflation gradually erodes purchasing power.
Instead, the objective is to take risks that are appropriate for your financial circumstances and long-term needs.
For someone approaching retirement, this may mean reviewing the balance between growth-oriented investments, more defensive assets and accessible savings.
For someone already retired, it may mean ensuring that the money needed for near-term spending is not overly dependent on the stock market performing well at precisely the right time.
The right allocation will vary from person to person.
A good investment strategy is not simply about maximising returns. It is about pursuing appropriate returns without taking more risk than your financial situation can reasonably support.
5. Stay Disciplined, but Review When Necessary
When markets fall, the temptation to act can be strong.
Some investors sell because they fear further losses. Others rush to buy because they believe prices must rebound soon.
Both decisions may be premature if they are based primarily on emotion rather than a clear assessment of the situation.
Trying to predict every market movement is difficult. To time the market successfully, investors must decide when to sell and when to reinvest. Getting both decisions right consistently is challenging.
Selling after a decline may lock in losses and leave an investor out of the market if prices subsequently recover. Buying simply because prices have fallen can also be risky if the underlying investment continues to deteriorate.
This is why a disciplined investment strategy can be valuable.
If your portfolio was built around a sound financial plan, an ordinary period of volatility does not automatically mean that plan should be abandoned.
However, discipline does not mean ignoring new information or holding every investment indefinitely.
Your circumstances may change. Your retirement date may draw closer. Your income needs may increase. An investment's fundamentals may weaken, or your portfolio may become more concentrated than intended.
These are legitimate reasons to review your strategy.
A sensible approach is to establish clear principles for when you will review, rebalance or change your investments, rather than allowing every market headline to dictate your next decision.
When markets fall, consider three questions:
Has my financial goal changed?
If you are still investing for the same long-term objective, the market decline may not require a complete change of strategy. If you need the money sooner than expected, your plan may need to evolve.
Have the fundamentals of my investments changed?
Look beyond the share price and consider whether the investments still meet the reasons you originally selected them.
Can my financial plan withstand further volatility?
If another significant decline would force you to sell investments to meet essential expenses, it may be time to review your allocation, cash reserves and income arrangements.
These questions will not predict what the market does next. They can, however, help you make decisions that are more consistent with your long-term financial interests.
The goal is not to remain invested at all costs. It is to remain committed to a sound plan while being willing to adjust when the facts or your circumstances change.
For people approaching retirement, the five fundamentals take on an additional significance.
When you are still working, you may have an active income to support your living expenses and continue contributing to your savings. After retirement, you may depend more heavily on accumulated assets and income streams to support your lifestyle.
A market decline during this transition can therefore create challenges beyond the temporary fall in portfolio value.
Consider two people who are both 62 years old and experience the same decline in their investment portfolios.
The first has sufficient accessible savings and other dependable income sources to meet their living expenses for the foreseeable future. They do not need to sell their long-term investments immediately.
The second relies heavily on portfolio withdrawals to fund monthly expenses. Even when markets fall, the bills still have to be paid.
If the second retiree sells investments at depressed prices to meet those expenses, fewer assets remain available to participate in a potential recovery.
This illustrates a risk known as sequence-of-returns risk: the timing of investment returns can have a significant effect on how long a retirement portfolio lasts when withdrawals are being made. Poor returns early in retirement can be particularly damaging because withdrawals during a downturn may leave a smaller portfolio to support future spending.
This is why retirement planning involves more than selecting investments with attractive long-term return potential.
It also involves planning how your different financial resources work together.
For Singaporeans, CPF LIFE can provide a foundation of lifelong monthly income. Depending on your payout level and expenses, it may cover some or much of your essential spending.
Your other savings and investments can then be planned around that foundation.
Some of the questions worth considering include:
- How much monthly income will I need in retirement?
- How much of my essential spending can be covered by CPF LIFE and other dependable income sources?
- How much additional income will I need from my savings and investments?
- Do I have sufficient accessible funds for emergencies and foreseeable expenses?
- Is my portfolio appropriate for both my near-term income needs and longer-term growth?
- What would happen if markets fell sharply during the first few years of retirement?
There is no universal answer. The right approach depends on your financial resources, commitments, goals and tolerance for risk.
Someone whose essential expenses are largely covered by dependable income may have more flexibility to keep a portion of their investments allocated to long-term growth.
Someone who depends heavily on portfolio withdrawals may need to pay closer attention to liquidity, withdrawal rates and the timing of potential losses.
The objective is not to eliminate every possible risk. That would be unrealistic.
It is to avoid relying on optimistic market assumptions to fund essential living expenses and to make sure your retirement plan can accommodate different market conditions.
A well-designed retirement plan should not require you to predict the next market downturn correctly. It should recognise that downturns can happen and account for how you will manage them.
The STI's sharp decline on 8 October 2026 is a timely reminder that markets can change direction quickly.
It is also a reminder that investment confidence should not depend on the assumption that markets will always rise.
No one can guarantee when the next correction will occur, how severe it will be or how quickly prices will recover. Nor can anyone promise that every investment will eventually return to its previous high.
What investors can do is prepare.
Know your investment time horizon. Diversify appropriately. Understand what you own. Match your risk to your financial needs. Stay disciplined, while remaining willing to review your plan when circumstances change.
And if retirement is approaching, take a broader view of your finances.
Look beyond the total amount you have accumulated. Consider how much income you need, when you will need it and how your CPF LIFE payouts, savings and investments can work together to support your desired lifestyle.
When markets are rising, it is easy to feel confident. When markets fall, a well-considered plan can help you focus on what matters rather than reacting to every headline.
You do not need to predict every market movement to prepare for retirement. But you do need to understand your financial needs, the risks you are taking and how your plan is designed to respond when markets become uncertain.
Because the purpose of investing is not simply to accumulate the biggest possible portfolio.
It is to help you build the financial freedom to live the life you want.
Don't just invest for a better future. Plan for a retirement you can live confidently through — even when markets get uncertain.
